AWS Q3 revenue growth surges 39%, capex stings Amazon's cash flow
Amazon Web Services revenue surged 39% in the third quarter compared to a year ago, but Amazon results fell short of expectations.
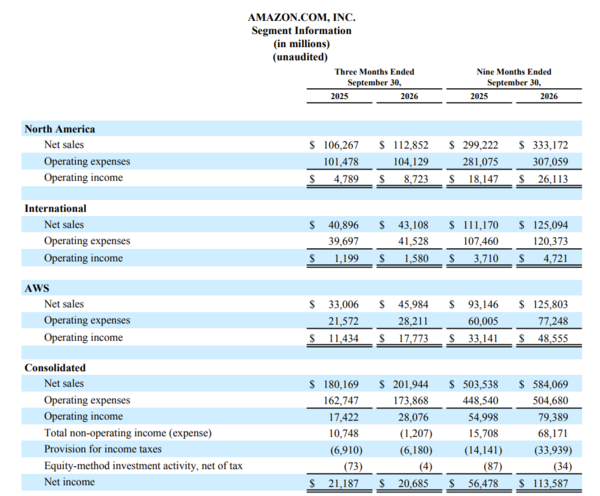
AWS reported operating income of $17.8 billion on revenue of $46 billion. That pace puts AWS on a $184 billion annual revenue run rate.
Parent company Amazon delivered net income of $20.7 billion, or $1.89 a share, on revenue of $201.9 billion, up 12% from a year ago. Amazon said the earnings decrease was due to a tough compare due to its investment in Anthropic.
Wall Street was expecting Amazon to report non-GAAP earnings of $1.96 a share on revenue of $202.26 billion.
By the numbers:
- North America e-commerce in the third quarter had operating income of $8.7 billion on revenue of $112.9 billion.
- International had operating income of $1.6 billion on revenue of $43.1 billion.
- Prime Day was pushed into the third quarter and boosted sales.
- AWS Lambda now has an annual revenue run rate of $1 billion.
- Free cash flow was negative $42.4 billion for the trailing 12 months due to investments in AI. A year ago, free cash flow was $14.7 billion.
CEO Andy Jassy said:
"Our AWS investment in functionality and infrastructure is working, with over 39% year-over-year revenue growth in Q3 ($184 billion revenue run rate) and projected revenue growth rates of over 40% both in 2027 and in 2028."
As for the outlook, Amazon projected fourth quarter sales between $240 billion and $247 billion, up 12% to 16%. The company said that it expects 2026 capex to be about $220 billion.
Speaking on an earnings call, Jassy said the following:
- "We believe that AWS can grow north of 40% in each of 2027 and in 2028, and be a $1 trillion revenue business in the next 5 to 10 years. We're in the very early days of this inflection, our strategy is working, and I expect it will for the foreseeable future."
- "We're installing an AI accelerator about every 14 seconds and almost as fast as we install capacity, customers are gobbling it up. Our core compute and storage revenue grew at their fastest rates in several years. Our operating margins have long been strong on our core offering, but rapidly improving on the AI side, too, well ahead of where they were on core at a similar time of evolution."
- "We continue to accelerate our CapEx payback and have even more conviction than we already had that the investment we're making in AWS will yield a much larger revenue and free cash flow generating business than we would have imagined a couple of years ago with strong return on invested capital."
- "it's important to remember that the vast majority of global IT spend, about 85% is still on-premises, and we're in a 10- to 20-year cycle where that equation will flip to the cloud. Conventional wisdom has been that linchpin workloads like mainframes or storage array networks would never move to the cloud. But these workloads are moving as AWS has built unique cloud substitutes and AI-driven migration capabilities to make this transition much easier."
- "After our launch of Graviton 5, backlog for prior generation Graviton instances still more than doubled quarter-over-quarter. And short-term capacity for prior generation training instances sell at a premium compared to the first half of the year. With training demand so strong, customers continue encouraging us to make it available outside of AWS we intend to do so late in 2027. Overall demand for AWS capacity remains exceptionally strong. Enterprises are still very early in using inference at scale, and yet inference already accounts for well over half of AWS' AI revenue and growing."
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Read morePublished
Author